Divorce can reshape your finances long after the legal process ends. Property division, debt, taxes, retirement accounts, and ongoing family expenses can all affect your financial position for years. Early organization gives you and your legal advisers reliable information to work with, which can reduce costly surprises.
Advice on protecting your family’s financial future often begins with the same principle: understand what you own, what you owe and which obligations could follow you after a major life change.
Build a complete financial record early
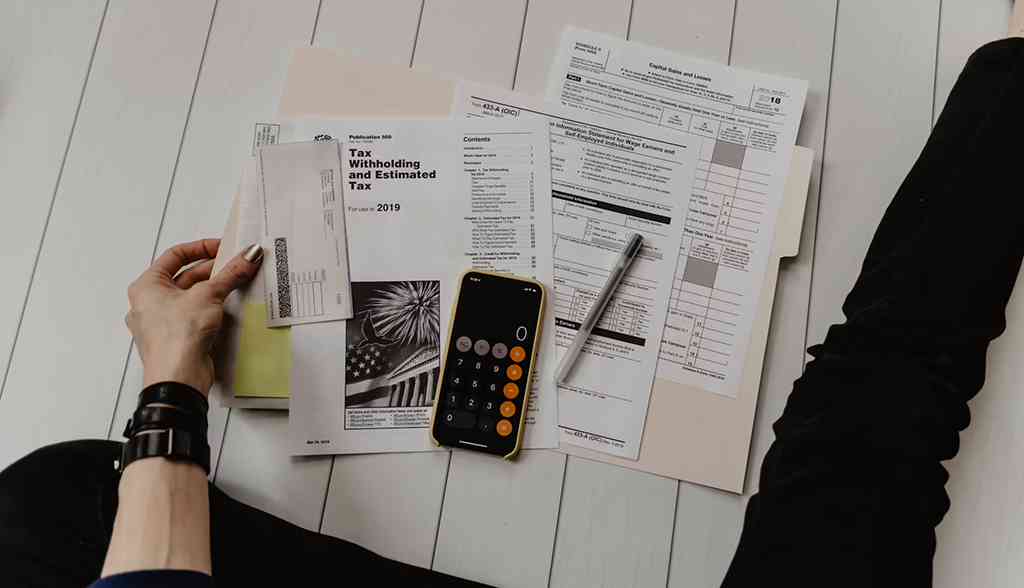
Start collecting financial documents as soon as divorce becomes a serious possibility. Gather recent tax returns, bank statements, mortgage records, loan agreements, retirement account statements and insurance policies. Include records for property acquired before the marriage since dates and funding sources may affect how an asset is treated.
Professional help can be especially valuable when business interests, multiple properties or significant retirement savings are involved. Men and fathers in Old Bridge who have concerns about complex asset division can consult divorce lawyers for advice tied to their circumstances.
Store copies in a secure location that only you can access. A dated inventory can also help establish account balances at a specific point in time.
Look beyond an asset’s current value
Two assets with the same stated value may produce very different financial results. A $300,000 retirement account, for example, may carry future tax obligations. A home valued at $300,000 comes with property taxes, insurance, repairs and possible selling costs.
Estimate both the short-term expense and long-term value of each proposed asset. If keeping a home would consume most of your monthly income, selling it may provide greater flexibility. Consider asking a financial professional to model several settlement scenarios over five or 10 years.
Don’t overlook less obvious property such as stock awards, deferred compensation, loyalty points, digital accounts or valuable collections. Accurate valuation matters because missing an asset during negotiations can permanently affect the final division.
Separate joint debts and protect your credit
A divorce agreement may assign a joint debt to one spouse, but the creditor can still pursue anyone whose name remains on the account. Review every credit card, personal loan and line of credit, then ask each lender what is required to close, refinance or transfer the obligation.
Check your credit reports for unfamiliar balances, late payments and accounts you may have forgotten. Freeze or close unused joint credit lines when your lawyer confirms that doing so won’t violate any standing financial restrictions.
Continue monitoring shared accounts until they’re formally closed. One missed payment can reduce your credit score and make a future apartment lease, mortgage, or auto loan more expensive.
Treat retirement and taxes as separate decisions
Retirement accounts require careful handling because a direct withdrawal or incorrect transfer may trigger taxes and early-distribution penalties. Some employer-sponsored plans need a court-approved order before funds can be divided. Ask your lawyer and a qualified tax professional which documents apply to each account.
Tax issues can also change the real value of a settlement. Review the tax basis of investments, potential capital gains on property, and the treatment of support payments under current law. Discuss who can claim eligible children as dependents and how any refund or outstanding tax bill will be handled.
Update beneficiary designations after the required legal approvals are in place. A divorce decree may not automatically change the beneficiary listed on every retirement plan or insurance policy.
Rebuild your financial plan around one household
Create a post-divorce budget using realistic numbers for housing, transportation, health coverage, child-related costs and savings. Expenses that once supported one shared household may now need to cover two separate homes. Include irregular costs such as annual insurance premiums, school activities and home maintenance.
Build an emergency reserve gradually, even if the first deposits are modest. Review your insurance coverage and update your estate documents as state law allows. You can also use this guide to protect your financial future when life changes as a broader checklist for adjusting accounts and financial goals.
Before signing a settlement, compare its terms with your monthly budget. A workable agreement should leave enough cash flow to meet routine obligations without depending on credit.
Financial protection during divorce depends heavily on accurate records and realistic projections. Before your next legal or financial meeting, prepare one clear list of assets, debts, account ownership, and unresolved questions. That document can keep discussions focused on the choices that will shape your finances after the case ends.